

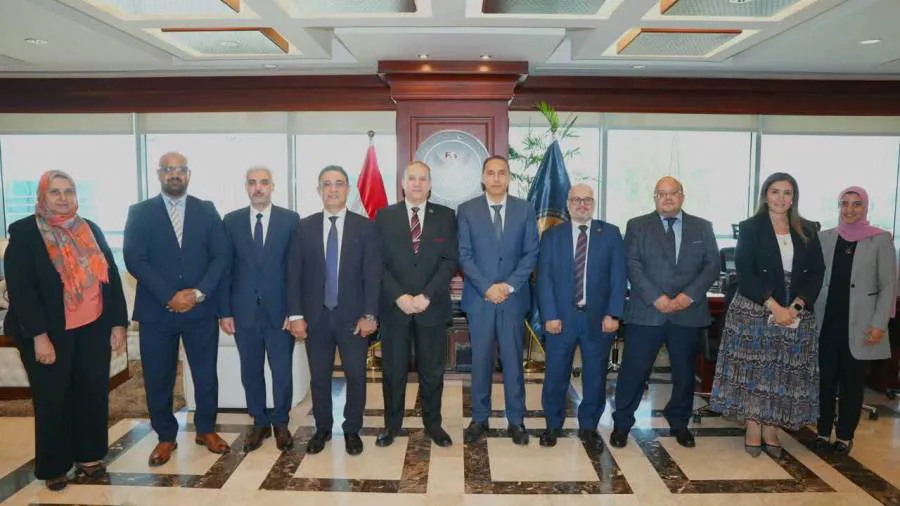
- The meeting aimed to strengthen efforts against money laundering and terrorist financing, including early detection, risk assessment and targeted financial sanctions
Dr. Islam Azzam, Chairman of the Financial Regulatory Authority:
- All entities are required to apply the updated version of the "customer due diligence procedures" and upgrade their internal systems
- Ongoing coordination between the FRA and the Unit to enforce the relevant legislation and decisions and raise awareness of their provisions
Hamdy Badawy, Assistant to the FRA Chairman: Updating oversight, governance and risk management frameworks is vital for institutions and a cornerstone for thriving activities
As part of ongoing cooperation between the Financial Regulatory Authority (FRA) and the Money Laundering and Terrorist Financing Combating Unit (EMLCU), the FRA hosted an expanded meeting bringing together members of the Unit's Research and Strategic Analysis Department and representatives of companies operating in non-banking financial activities, including board chairmen, chief executives and compliance officers. The meeting aimed to strengthen efforts to counter money laundering risks and detect them early.
Dr. Islam Azzam, Chairman of the FRA, welcomed the Unit's representatives and praised the pivotal role of the Unit, headed by Counsellor Ahmed Saeed Khalil, Chairman of its Board of Trustees, in coordinating continuously with the FRA as one of the Egyptian state's regulators. That coordination aims to enforce the legislative and regulatory frameworks for combating money laundering and terrorist financing, extend them across economic sectors and raise awareness of their provisions. He also praised the Unit's efforts in training, transferring expertise to state bodies and raising public awareness.
The FRA Chairman stressed his commitment to supporting the efficiency and effectiveness of anti-money laundering and counter-terrorist financing controls in the activities the FRA supervises. He pointed to Circular No. (5) of 2026, issued a few days ago, which requires all institutions in the capital market, insurance and non-banking finance sectors to comply with the updated version of the "Due Diligence Procedures for Customers of Financial Institutions Supervised by the Financial Regulatory Authority", issued by the Unit last September.
Dr. Islam Azzam explained the importance of the FRA's recent decisions to upgrade the digital verification of customer data and identity through one-time passwords (OTP), and the real-time link between consumer finance and medium, small and micro enterprise finance providers and the credit bureau. He also noted preparations for a full link between consumer finance companies' databases and the FRA's database. These steps help detect negative phenomena and various risks early, chiefly fraud and money laundering, while improving operational quality, ensuring sound credit granting and reducing the likelihood of default.
During the expanded meeting with company representatives, the Unit's representatives gave an in-depth presentation on money laundering and terrorist financing risks and the importance of applying targeted financial sanctions. These include asset freezes and prohibitions that prevent funds or assets from being made available to designated persons or entities, as well as the sanctions lists of persons and entities subject to those measures under UN Security Council resolutions, and the domestic lists issued under Law No. (8) of 2015 on Terrorist Entities and Terrorists.
The meeting also covered customer due diligence and identity verification, indicators of high-risk cases, the applicable legal arrangements, how to identify the predicate offence and the beneficial owner, procedures relating to financial institution staff, customer acceptance policy, and ongoing due diligence through transaction monitoring. Participants stressed that anti-money laundering and counter-terrorist financing requirements are not an obstacle to achieving financial inclusion goals or providing non-banking financial services.
The Unit's representatives stressed the importance of companies having, and retaining, data, information and documents that show the measures they take, to demonstrate their ability to handle risks and suspicious transactions in line with the controls and rules applied nationally. They also stressed the need to review these rules on an ongoing basis so that results can be measured and the efficiency of internal systems confirmed.
For his part, Hamdy Badawy, Assistant to the FRA Chairman, said the meeting reflects the commitment of the FRA and the companies it supervises to tightening compliance with anti-money laundering and counter-terrorist financing systems, and to developing internal practices in line with the nature of the risks linked to each activity and those that may arise as markets keep evolving.
He added in his remarks that developing oversight, governance and risk management frameworks in the non-banking financial sector is vital for institutions to keep pace with international and local standards, and a cornerstone for maintaining service quality and thriving markets, increasing the sector's contribution to the national economy.
Hamdy Badawy highlighted the response required from the sector's institutions to Circular No. (5) of 2026: circulating the updated version of the "Due Diligence Procedures for Customers of Financial Institutions Supervised by the Financial Regulatory Authority", issued by the Unit, to all affiliates, branches, departments and staff, so that they are fully familiar with it and apply it in full, and making whatever updates are needed to policies, procedures and internal control systems to align them with the requirements of the updated due diligence procedures.
The regulatory framework for non-banking financial activities includes strict provisions, chief among them Decision No. (161) of 2024 on regulatory controls for combating money laundering and terrorist financing, which requires those it covers to establish a clear policy and internal rules, procedures and systems for risk assessment, and Decision No. (186) of 2024 on verifying the accuracy of customer data. These rest on Anti-Money Laundering Law No. (80) of 2002, its executive regulations and related laws.

Comments
No comments yet. Be the first!