

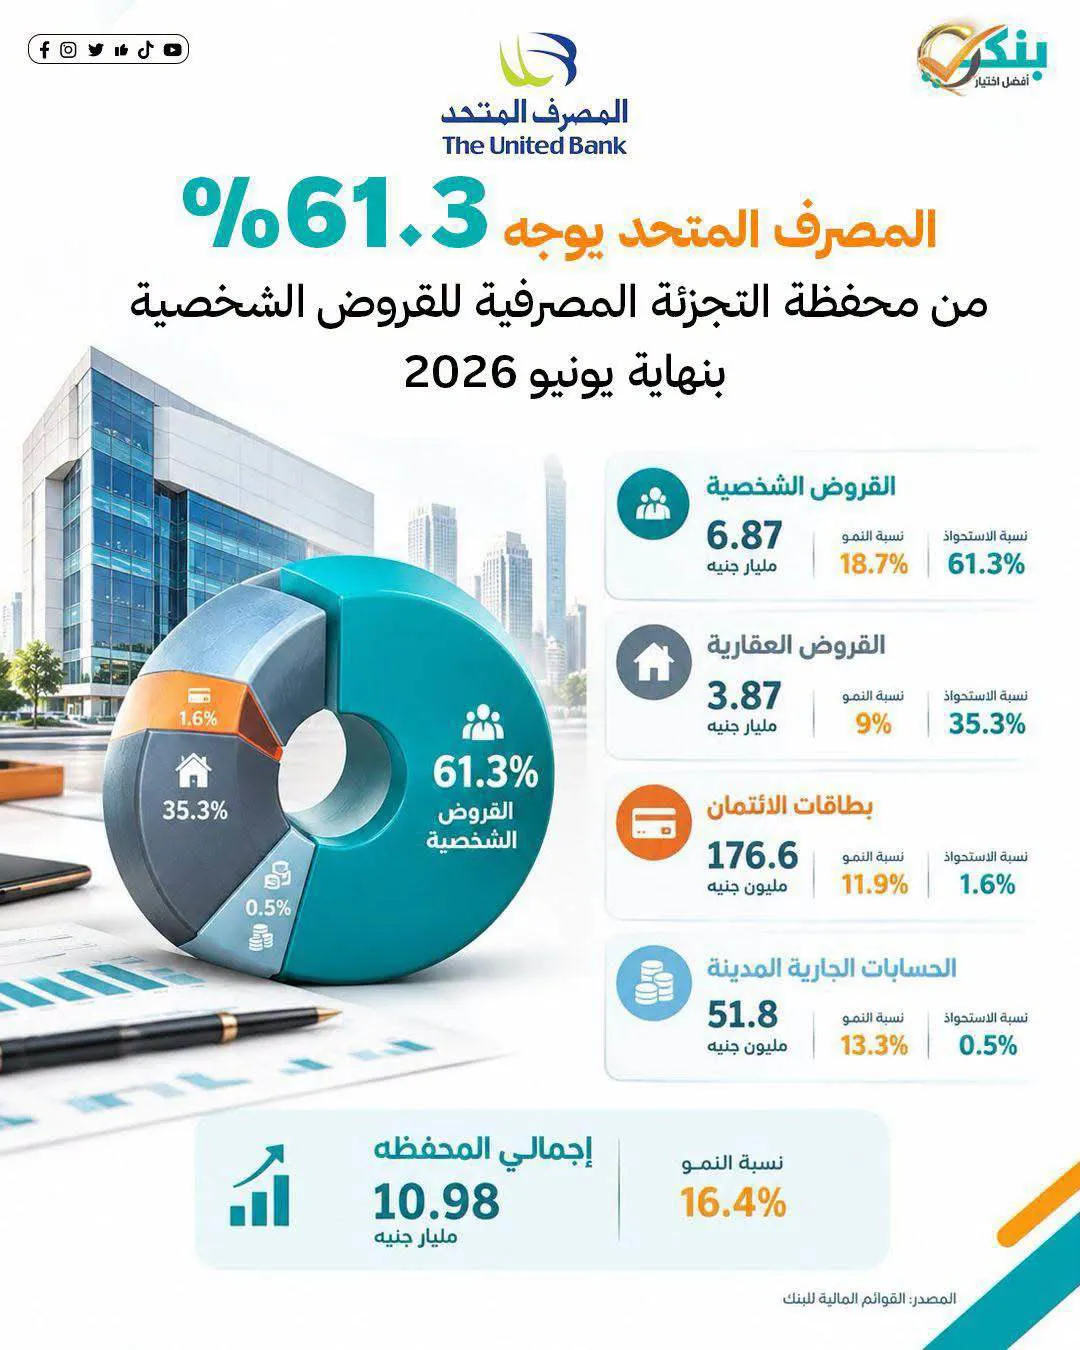
The United Bank's retail loan portfolio continued to grow strongly in the first half of 2026, with the total retail portfolio reaching about EGP 10.98 billion at the end of June 2026, compared with EGP 9.43 billion at the end of December 2025. That is an increase of EGP 1.55 billion, or growth of 16.4% in 6 months.
Personal loans were the largest component of the retail portfolio, rising to EGP 6.87 billion at the end of June 2026 from EGP 5.67 billion at the end of December 2025, an increase of EGP 1.06 billion and growth of 18.7%. Personal loans accounted for about 61.3% of the total retail loan portfolio.
Mortgage loans came second, rising to EGP 3.87 billion at the end of June 2026 from EGP 3.56 billion at the end of December 2025, an increase of EGP 318.7 million and growth of 9.0%. They accounted for about 35.3% of the total retail loan portfolio.
The credit card portfolio grew by 11.9% in the first half of the year to EGP 176.6 million at the end of June 2026, from EGP 157.7 million at the end of December 2025, an increase of EGP 18.8 million. It accounts for about 1.6% of the total portfolio.
Retail overdrawn current account balances also rose to EGP 51.8 million at the end of June 2026 from EGP 45.7 million at the end of December 2025, an increase of EGP 6.1 million and growth of 13.3%. Their share stands at about 0.5% of the total retail loan portfolio.
Banky's view:
The indicators of The United Bank's retail loan portfolio point to a balanced strategy that relies on personal loans as the main growth driver, at more than 61%, alongside a strong and pivotal weighting for mortgage finance of more than 35% of the portfolio. This reflects the bank's focus on diversifying its long-term financing tools and supporting the mortgage finance sector, alongside its direct retail banking services.

Comments
No comments yet. Be the first!