

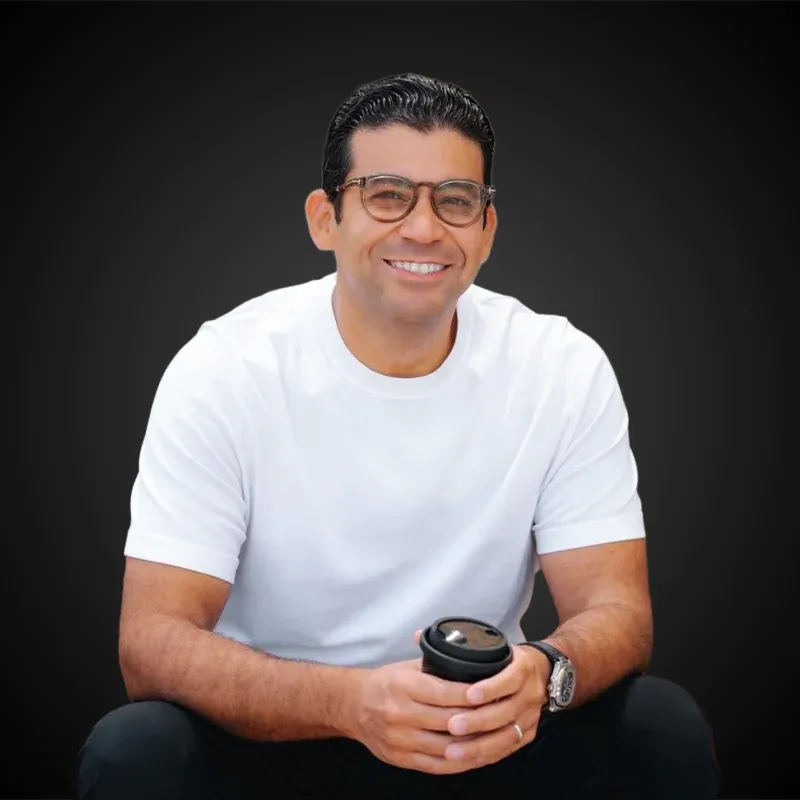
Rashwan Hammadi's career spans more than twenty years at Commercial International Bank – Egypt (CIB), where he moved through finance, strategic planning, small and medium-sized enterprises, retail banking and financial inclusion, before going on to lead the digital bank Yomo through its establishment phase and preparations to launch its services. This path gives him a varied background that combines strategy-making, product development, customer-segment management and building new banking business models.
His leadership of Yomo comes as CIB moves to set up an independent digital bank, after receiving preliminary approval from the Central Bank of Egypt (CBE) in August 2026, with plans to invest USD 300 million in the digital platform owned by Yomo Holding. The approval marks the start of completing the incorporation requirements and operational and technological readiness, ahead of obtaining the approvals needed to serve customers.
Starting out in finance
Hammadi began his banking career at CIB in 2004 in the finance division, then completed the bank's credit and investment training program in 2006, adding knowledge of credit analysis and company valuation tools to his financial expertise.
In 2007 he moved to strategic planning, before taking charge of the division in 2009. His responsibilities included preparing business plans and strategies and helping develop the governance framework for the bank's committees, a stage that broadened his work from financial tasks to planning business development and setting growth priorities.
Leading SMEs and payment acceptance
In 2013 Hammadi became head of the small and medium-sized enterprises (SME) and payment acceptance division, where his responsibilities extended to marketing and sales strategies, relationship management and developing products for this customer segment.
He led this business for more than seven years before moving on to broader responsibilities in retail banking. This stage gave him direct exposure to the needs of business owners, combining the development of financing solutions, payment services and banking relationship management.
Retail banking and financial inclusion
Hammadi became head of retail banking customer segments and products in March 2020, then moved to lead retail banking from August 2022. His responsibilities included developing and executing strategies for customer segments, products, sales and service channels for individuals and SMEs.
His official CIB biography records his membership of the executive committee and his contribution to building the SME business, launching innovative banking solutions and products, and developing a digital banking platform and a dedicated service model for Egyptians living abroad. The bank also credits the period in which he led these activities with achieving the largest market share among private-sector banks in household lending and deposits.
Chairing Commercial International Finance Company
Hammadi's responsibilities extended to non-banking financial services as non-executive chairman of the board of Commercial International Finance Company (CIFC), a CIB subsidiary specializing in factoring and mortgage finance. The company was established in June 2022 and began commercial operations in April 2024.
According to the bank's statement, the company's factoring portfolio exceeded EGP 4.1 billion, while outstanding balances reached about EGP 2.07 billion at the end of the second quarter of 2025. Hammadi linked the company's launch to widening the range of services offered to customers through specialized financing channels, with a focus on the needs of SMEs and supporting their ability to expand and produce.
Yomo: moving on to build a fully fledged digital bank
Leading Yomo is the latest stage in Hammadi's career: he is responsible for developing a banking experience built digitally from the ground up. The project aims to offer financial services that are easier to access and use for individuals and business owners, drawing on CIB's expertise and governance framework.
The model is based on building a fully fledged digital bank, with an operating system and technology infrastructure designed for that purpose from the outset. According to the project's stated vision, artificial intelligence is one component of this model, supporting service development, simplifying money management and meeting customers' changing needs.
USD 300 million to deliver the plan and target profitability
The investment earmarked to deliver Yomo's plan in full is about USD 300 million. According to Hammadi's statements published in September 2026, the amount is sufficient for the planned establishment, operation and growth phases, and there were no concerns at the time about needing additional funding.
The plan aims to start generating net profit before the end of the five-year period, without announcing a specific date for reaching profitability. This remains a target within the business plan, tied to delivering the operating and growth phases.
Technology readiness and licensing requirements
In his statements published in September 2026, Hammadi set a period of three to four months to complete the technology infrastructure, cybersecurity systems and technical setup, to be followed by a readiness review in coordination with the Central Bank of Egypt and the addressing of regulatory comments and requirements.
The start of trial operations depends on obtaining the final operating license, so he did not set a final launch date. He described securing the license by the end of the first half of 2027 as an important achievement for the project, without presenting that timing as a confirmed date for starting to take on customers.
Ten million customers in five years
Yomo aims to reach about ten million customers in its first five years of operation, according to Hammadi's interview with CNBC Arabia in August 2026. The bank's strategy starts with retail services, then expands to serve small and micro businesses, with a focus on the experience of obtaining a product, using it and the support that comes with it.
Target segments include individuals in Egypt, Egyptians living abroad, and owners of small and micro businesses. The technology infrastructure is being designed to handle millions of customers, and possibly tens of millions in the long run, making scalability a core element of the business model.
Artificial intelligence and risk-management expertise
Hammadi focuses on using data analytics and artificial intelligence to understand customers' financial behavior, improve credit assessment and tailor offers and solutions to each customer's needs and financial capacity. He believes the expertise of the Yomo team, together with CIB's accumulated experience in risk management, control and governance, supports the digital bank's competitiveness.
This vision ties in with his leadership philosophy, which focuses on developing talent, flexibility and continuous improvement, and on encouraging teams to innovate and learn from experience, supporting the delivery of accessible financial solutions to individuals and businesses.
Academic background
Rashwan Hammadi holds a bachelor's degree in commerce from Sohag University and an MBA from the University of Chicago Booth School of Business, which he earned in 2018. These qualifications complement his long practical experience across strategy, credit, products and banking service channels.

Comments
No comments yet. Be the first!