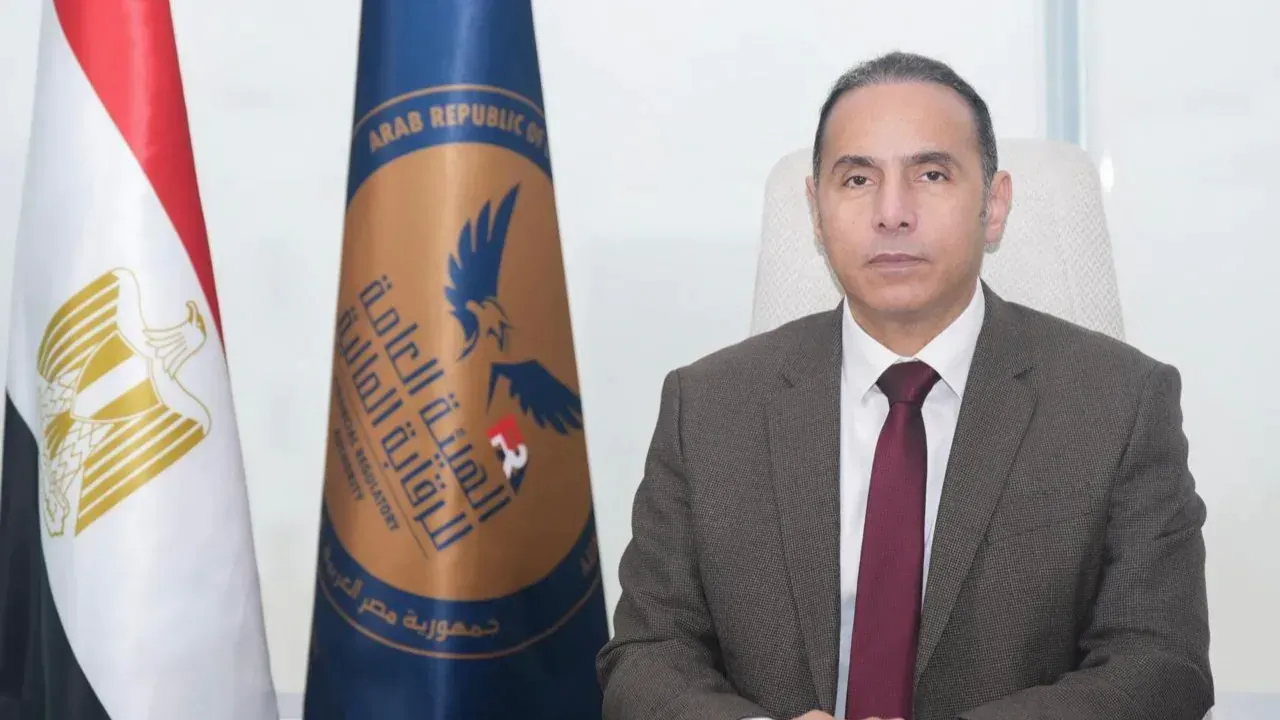
Head of the Financial Regulatory Authority:
The new model contract aligns with market developments and achieves a balance between supporting companies and protecting customer rights.
Companies are required to apply the model contract when financing a single transaction or multiple goods and services.. and users of prepaid cards
Companies may add other provisions after obtaining no objection from the authority.. and a three-month grace period to rectify the situation
It is necessary for the client to review the contract before signing it.. and to provide a digital copy on the dedicated electronic application
Companies must adhere to the principles of security and integrity.. and refrain from any actions that may constitute harm to the client, especially when collecting dues.
The client is committed to the accuracy of the data and not to facilitate the financing and using it for the specified purpose only.. and to pay the instalments on the agreed dates
The model contract addresses cases of early repayment and late payment penalties.. and prohibits amending the contract without the client's consent.
Determining cases of automatic termination of the contract and the company's rights to suspend the client's eligibility to purchase goods from the financing limit
Continuing the efforts of the Financial Regulatory Authority to enhance market stability and facilitate the application of regulations governing non-banking financial activities; the head of the authority, Dr. Islam Azam, issued a decision regarding the standard contract between the company and the client in the consumer finance activity, which clearly defines the rights and obligations of each party and addresses many contractual and practical issues that have emerged recently, amid the steady expansion of the activity.
The decision includes a model for the contract that the company concludes with the client to obtain financing for purchasing more than one good or service, and another model for the contract that the two parties conclude for a single consumer financing transaction. Companies are required to apply these two models instead of the models approved by the authority in 2021 following the issuance of Law No. 18 of 2020 regulating consumer finance activities.
Dr. Islam Azam stated that the decision includes several developments to keep pace with market trends that ensure a balance between the growth of the activity and supporting companies and providing maximum levels of protection for consumer rights, and it obliges consumer finance companies to use the two contract models attached to it (for a number of goods and services or a single consumer financing transaction) when concluding consumer financing contracts with clients, without violating other obligations for companies practicing the activity according to the Financial Technology Law in non-banking financial activities No. 5 of 2022.
He added that all mandatory data required to be recorded in the contract must be recorded digitally, and that the terms must be clear and legible, and that the company must provide the client with the contract before signing it, and that a digital copy of it must be made available through the dedicated application.
It is clarified that companies may add other provisions to the contracts - contrary to those stipulated in the standard contract - provided that they obtain prior approval from the authority for such additional provisions.
Dr. Islam Azam emphasized the necessity for companies to adhere to the principles of security and integrity in providing services to clients and to refrain from any actions that may harm the client, especially when collecting dues.
The new standard contract for consumer financing includes 19 clauses and begins with a set of necessary data specific to the company and the client, and stipulates the commitment of both parties to the provisions of the law and the decisions of the Financial Regulatory Authority and its regulations.
The contract expands to clarify important definitions in the consumer financing process to inform the client about the meaning of the consumer financing limit, the value of the good or service, the electronic application, and the network of merchants and service providers in consumer financing, and the prepaid card used in consumer financing.
Then it clearly explains the subject of the contract and the purpose of the financing and details the procedures for obtaining it, and specifies the characteristics of the goods and their specifications and defines them in a clear manner, and states that the client does not have the right to return to the company in the event of a defect in any of the goods or services provided without violating the provisions of the Consumer Protection Law.
The standard contract obliges the company to specify the consumer financing limit for the client, and the maximum limit for the annual interest rate, and to specify whether it is fixed or variable, and the maximum limit for administrative fees with all details and the fees that are due to it.
And to address some improper practices regarding late fees, the decision obliges companies to specify the maximum limit for the late interest rate in the contract, and that it should not exceed the total amount of late interest calculated on the client throughout the financing period for the amount not paid from the principal of the financing, preventing manipulation and exaggeration in such late fees, which would burden the clients excessively.
The standard contract stipulates in clause five - for the first time - a set of obligations clearly stated for the company, starting with the necessity of the diligent man's care in implementing its obligations, and ensuring the financial solvency of the client and inquiring about it before granting financing from the consumer financing company to ensure its ability to pay the instalments of the financing, provided that it does not exceed the total monthly instalments of the client to 50% of its total monthly income.
The new obligations include informing the client before financing the purchase of any good or service, the value of the good and the value of the financing and the duration of repayment and the annual interest rate and the administrative fees and the total instalments of the financing (principal and interest) and the instalment of the financing (principal and interest) and the due date of the instalment and the late fees and the early repayment fees, and the consumer financing limit, through the dedicated electronic application or any other means, provided that this information remains available after the purchase transaction.
And the standard contract warns the company against collecting the client's obligations while the financing operations are ongoing, as it states that it should allow the client to pay the dues owed to it, each in its own right, without collecting them, until it is allowed to deal with the sellers or service providers separately regarding each good or service obtained.
The company must comply with the client's request to disclose the account statement if requested, through the electronic application or any other means, which must include at least the details of the goods and services subject to financing, their value, the outstanding dues, and the total amount of each instalment, and the details of the interest and administrative fees in a detailed manner, and the duration of the outstanding repayment, and the late fees if any, with the right of the client to contest with the company regarding any amounts stated in the account statement within 15 days from the date of sending it to him.
As for the obligations of the client stipulated in the standard contract, they include the accuracy of the data and its correctness, and the company must inform it of any updates that occur to it, and the use of the granted financing for the purpose of purchasing goods and services for consumer purposes and not using it for any other purposes, and the total repayment of the instalments according to the amounts and specified dates, and maintaining the confidentiality of its account data in the electronic application, and notifying the company in case of loss or theft or damage to the prepaid card or not receiving it.
And to prevent the manipulation of mobile phone numbers and their use for unauthorized purposes, the standard contract obliges the client to confirm the accuracy and validity of the registered mobile phone number with the company, and he bears full responsibility for that, along with the necessity of notifying the company within 5 days at most in case of changing the number or losing it or its theft or the service being interrupted from it or transferring ownership to another party.
And on the part of the goods, it is also permissible to facilitate the goods or services subject to financing by selling them and obtaining cash funds, and obtaining financing in a manner that may lead to deception or misrepresentation of the company, and allowing any other party to use the dedicated electronic application for the client.
And to solve the problems of early repayment that are common between clients and companies, the standard contract specifies a clause that clearly regulates this matter in a balanced manner that prevents mixing between the value of the good or service and the applicable interest rate on the instalment. Where it allows the client to pay all the outstanding amounts owed to him or part of them before the repayment date, and in return, the company has the right to deduct the financing cost for the month in which the early repayment occurred, and it may add an early repayment fee at a specified percentage of the principal amount that the client wishes to repay early, after deducting the interest.
The model contract preserves the rights of the company; it stipulates its right to suspend any validity for the client to purchase goods or obtain services from the financing limit stipulated in the contract if the client defaults on the payment of two consecutive instalments on the agreed-upon due dates, and if it is proven that he provided incorrect or misleading data, information, or documents that affect the decision to grant financing, considering the contract to be automatically terminated in certain cases, including: using the financing for purposes other than consumption, facilitating the sale of goods or services, and listing on terrorist lists.
In achieving balance between the two parties of the contract and adhering to the principle of "the contract is the Sharia of the contractors," the decision prohibits the company from amending the contract unilaterally.
In cases of financing a single purchase, the company must notify the client before the amendment, and the client must express his consent or objection within a week of being notified.
In cases of financing multiple goods and services and a prepaid card system; if the company wishes to amend any of the terms related to the financing amount or interest rate or administrative fees or the amount of the early repayment, or any other provisions, the client must be notified before making the amendment, and the client must also express his consent or objection within 5 days from the date of notification, and his failure to respond during that period is considered an implicit agreement to the amendment, with the amendment applying only to future financings.
The model contract provides mechanisms for resolving disputes; the first of which is through the judiciary, specifically the economic courts, in disputes and disagreements regarding claims or interpretations or termination or annulment, and the second mechanism is an agreement between the two parties on arbitration before the Central Egyptian Arbitration Center for resolving non-banking financial disputes established by a decision of the President of the Republic No. (335) for the year 2019.
The decision is expected to be published soon in the "Egyptian Gazette" and will be implemented within three months from the date of publication, and companies must amend existing contracts for clients during that period.
It is worth noting that the authority issued during the current year 2026 a number of important decisions to enhance the efficiency of consumer financing activity, such as requiring companies to link instantaneously with the credit inquiry company, and using the one-time password (OTP) to govern the customer identity verification system, and adding behavioral analysis evaluation to the customer inquiry system, and prohibiting consumer financing for gold and silver, and linking the companies' data rules with the authority, in addition to issuing the first comprehensive guide for the rules and regulations of the activity in September of last year to facilitate companies' compliance with regulatory requirements.
Comments
No comments yet. Be the first!