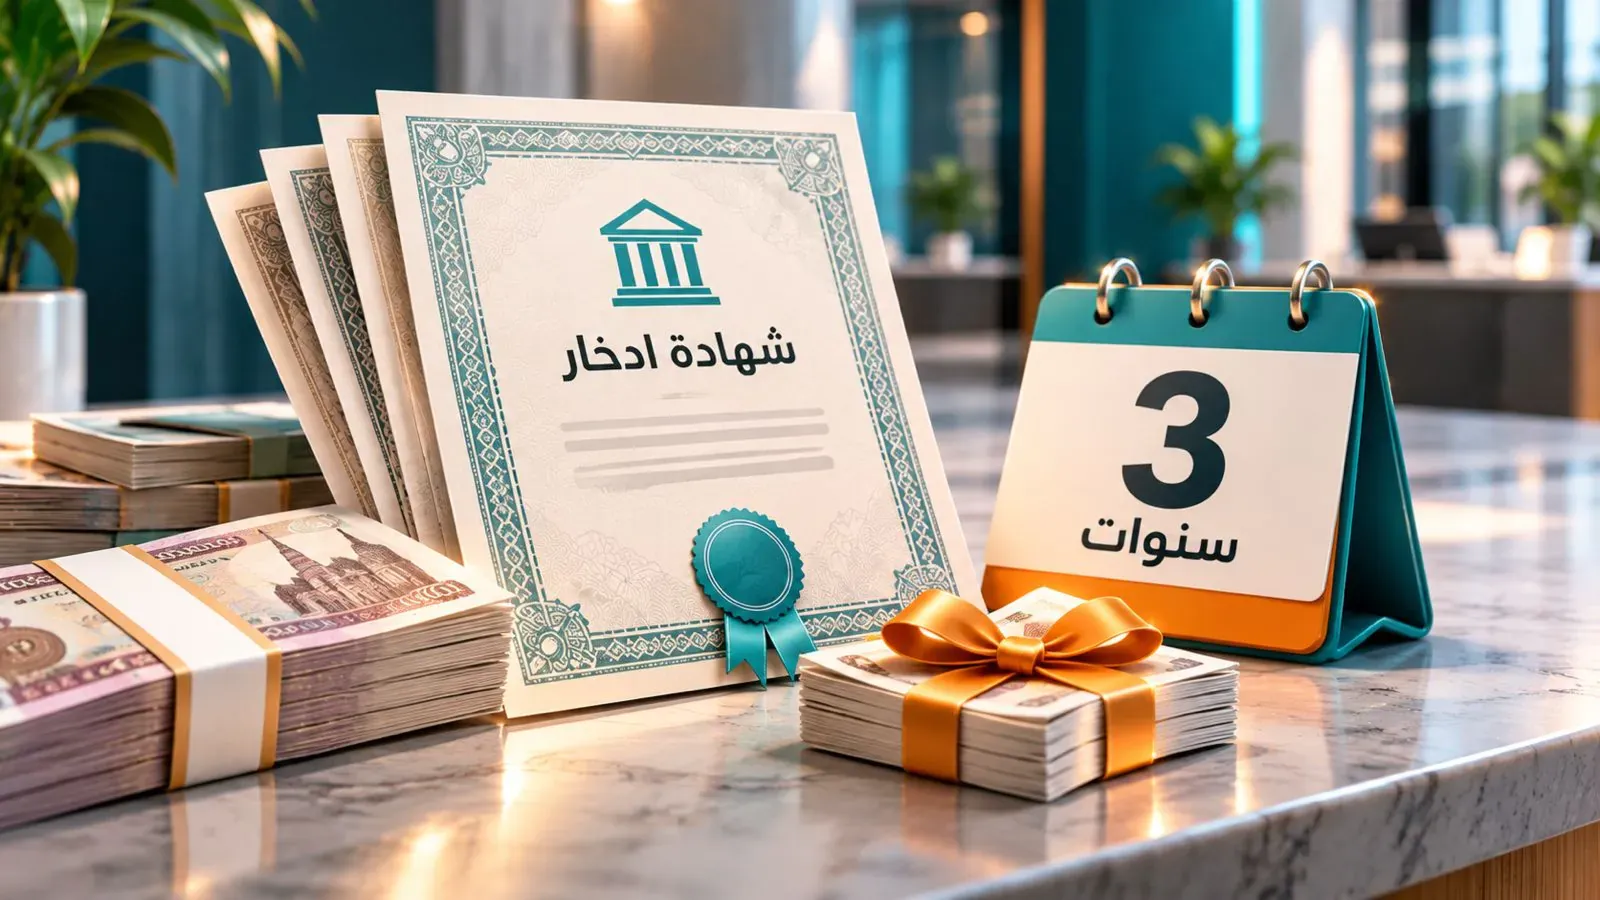
Savings certificates with a fixed daily interest represent one of the suitable options for small savers looking to achieve a regular income from their savings, especially with the availability of a fixed daily interest throughout the duration of the certificate, providing clients with periodic liquidity to help meet their financial needs, while benefiting from stable interest rates for a period of 3 years.
The available savings certificates vary for clients in terms of interest rates and the minimum purchase amount, as some issuances start from EGP 1,000 only, allowing the opportunity to invest small amounts and benefit from daily interest without the need to build a large capital.
Emirates Savings Certificate from Arab African International Bank
Interest: 18% per annum
Payout frequency: Daily
Certificate duration: 3 years.
Minimum purchase amount: EGP 1,000
Banky Analysis
Loading…
Returns
Loading…
Amount & term
Loading…
Withdrawal & renewal
Loading…
Our take
Pros
- Highly flexible variety in drainage cycles.
- Complete stability (fixed return): Once the certificate is linked, the interest rate is fixed for the entire 3-year period.
- Customers can apply for Secured
Cons
- The certificate cannot be redeemed or liquidated prior to the expiration of six months from its issuance date. In the event of early liquidation, the bank applies a deduction schedule to the return, with the deduction amount decreasing progressively based on the year in which the liquidation takes place.
Our take
The Arab African International Bank’s "Emerald" fixed-yield certificate is one of the most prestigious and renowned savings certificates in the Egyptian banking market. It offers a wide range of features designed to meet diverse customer needs. The Emerald fixed-yield certificate is a robust, secure, and highly reliable product, backed by the bank's excellent reputation in serving individual investors. It is an ideal choice if you seek complete financial stability and a major commercial bank that offers highly flexible profit payout options—particularly if you prefer annual returns or a cumulative return structure that allows you to reinvest capital into other assets, such as gold or real estate.
The ideal choice for those with boundless ambition, offering exclusive benefits and competitive interest rates.
User ratings
Prime certificate from Bank saib
Interest: 17.25% per annum
Payout frequency: Daily
Certificate duration: 3 years.
Minimum purchase amount: EGP 1,000
Banky Analysis
Loading…
Returns
Loading…
Amount & term
Loading…
Withdrawal & renewal
Loading…
Our take
Pros
- A combination of a high return and flexible payout options, with the ability to choose between daily and monthly interest and borrow against the certificate.
Cons
- Early redemption is available only after six months and is subject to the bank’s redemption schedule, limiting flexibility for early exit
Our take
The Prime Certificate from saib is a strong option for customers seeking a high fixed return with flexible interest payout options. It offers 17.75% with monthly payouts or 17.25% with daily payouts, with a minimum investment starting at just EGP 1,000. The certificate also allows borrowing against its value and early redemption after six months according to the bank’s redemption schedule, while offering convenient issuance through branches or internet banking. However, early redemption is subject to the bank’s redemption schedule, and its three-year term may not suit customers looking for longer-term savings.
A high-yield fixed-rate certificate offering up to 17.75% with monthly payouts, a minimum investment of EGP 1,000, and flexible payout options.
User ratings
Example with numbers.. Investing EGP 50,000 in savings certificates
First: Emirald savings certificate from Arab African International Bank
Investment amount: EGP 50,000.
Annual interest rate: 18%.
Annual interest: EGP 9,000.
Approximate daily interest: EGP 24.66.
Total interest over 3 years: EGP 27,000.
Total amount at the end of the term: EGP 77,000, including the principal and interest.
Second: Prime Certificate from Bank saib
Investment amount: EGP 50,000.
Annual interest rate: 17.25%.
Annual interest: EGP 8,625.
Approximate daily interest: EGP 23.63.
Total interest over 3 years: EGP 25,875.
Total amount at the end of the term: EGP 75,875, including the principal and interest.
Banky
The three savings certificates with daily interest hold special importance for small savers, given their ability to combine fixed interest and regular payout frequency, providing clients with a daily income source that can be used to cover various expenses instead of waiting for a monthly or quarterly interest payout, in addition to the reduced minimum purchase amount that allows a wider range of clients to invest their savings according to their capabilities.
Comments
No comments yet. Be the first!